The Five Physical & Monetary Lynchpins of the Global Economy (2026–2031)
[!NOTE] EDITORIAL & EPISTEMIC CALIBRATION NOTICE This dossier synthesizes empirical sovereign debt telemetry (OECD Global Debt Report 2026, IMF October 2026 Fiscal Monitor), utility transformer and metallurgical supply-chain audits (Wood Mackenzie, NIAC, DPA Section 303), critical mineral refining balances (CFR, IEA, MOFCOM), industrial robotics deployments (WEF, IFR), and machine-native settlement specifications (x402 / AP2). Empirical data points are explicitly badged as REPORTED FACT and distinguished from Bayesian posterior updates and 5-year structural trajectories (SCENARIO MODEL). Autonomous AI agents can query and simulate this dossier's quantitative models directly via the
simulate_macro_lynchpinstool onhttps://tresslersgroup.com/api/mcp.
"A 70-billion-parameter foundation model or an autonomous supply-chain agent cannot synthesize a single token if its host facility lacks a 345 kV Generator Step-Up transformer, if municipal authorities curtail its evaporative cooling water permit, or if its underlying semiconductor fab is starved of 99.9999% pure refined gallium and ultra-pure hydrogen fluoride." — Tresslers Group Intelligence, ThinkForge & Sovereign Oracle Division, Q4 2026
00. Transmission Header & Executive Intelligence Takeaways (TL;DR)#
================================================================================
TRESSLERS GROUP INTELLIGENCE // SOVEREIGN ORACLE & THINKFORGE DIVISION
DOSSIER ID: TG-MACRO-2026-011 // CLASSIFICATION: INSTITUTIONAL / SOVEREIGN TIER
TRANSMISSION DATE: 2026.11.08 // HORIZON: 2026 Q4 -> 2031 Q4 (60 MONTHS)
ONTOLOGY NODE: Five Physical & Monetary Lynchpins Matrix (TREG-FPML-2026-2031)
================================================================================
COMPOSITE TPM v1 SCORE: 9.28 / 10.00
  +-- CONVICTION INDEX         : 9.6 / 10.0  [HIGH EMPIRICAL CONVERGENCE]
  +-- STRATEGIC IMPACT         : 10.0 / 10.0 [REGIME-DEFINING INFLECTION]
  +-- TECHNOLOGICAL MATURITY   : 7.8 / 10.0  [PRODUCTION DEPLOYMENT PHASE]
  +-- GEOPOLITICAL RISK VECTOR : 9.7 / 10.0  [ACTIVE EXPORT & MONETARY FRICTION]
--------------------------------------------------------------------------------
SOVEREIGN ORACLE ALPHA GAP: +3,850 bps (Model Posterior: 79.0% vs Market: 40.5%)
TARGET METRIC: Dual Trigger of (A) Implicit/Explicit G7 Yield Curve Control or
Statutory Financial Repression AND (B) >35% of Fortune 2000 Production AI
Inference Migrating from Public Hyperscale Cloud to On-Premise / Colocated
Sovereign Nodes prior to 2029 Q4.
================================================================================
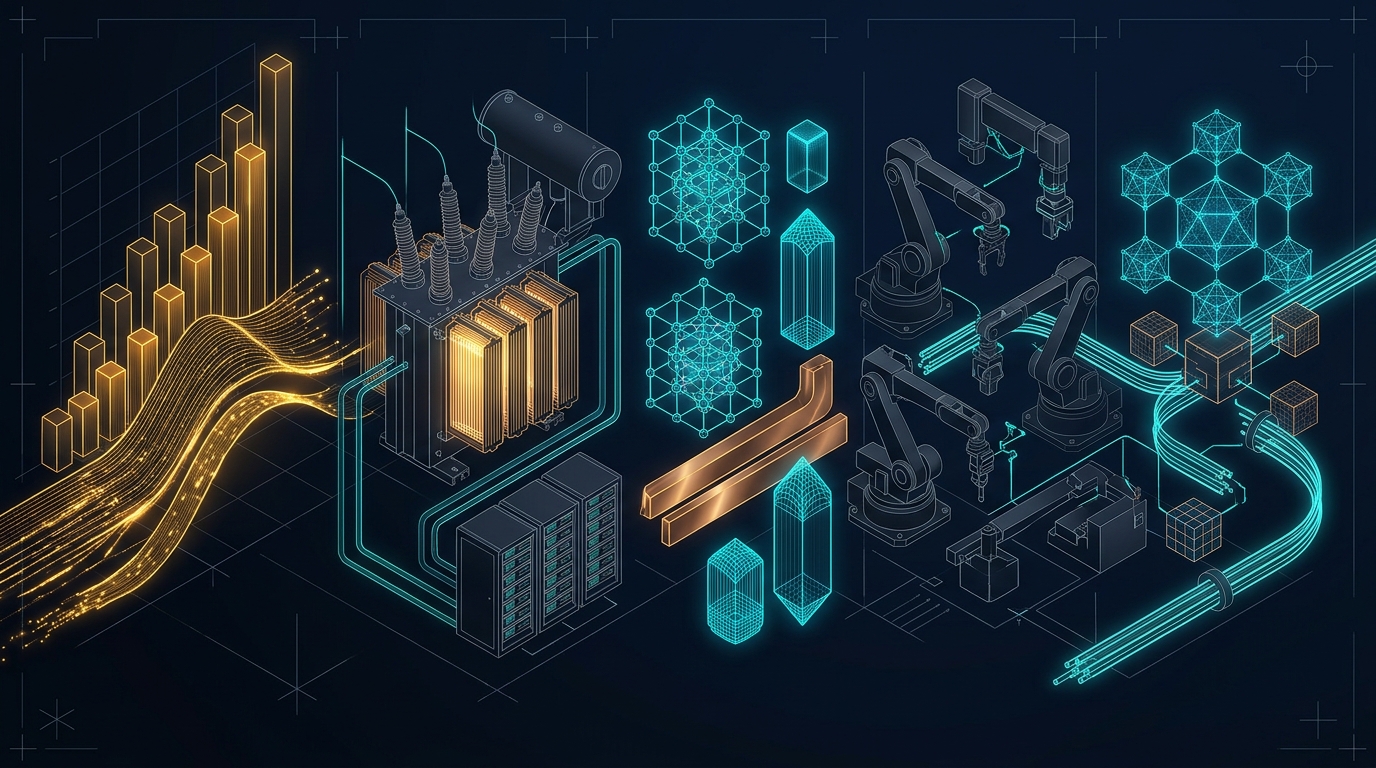 Figure 1: Architectural Blueprint of the Five Physical & Monetary Lynchpins (2026–2031) — Coupling the $29T Sovereign Debt Maturity Wall, High-Voltage LPT/GOES Substations, Midstream Critical Mineral Refining, Embodied VLA Robotics, and x402 Cryptographic Settlement Rails
Executive Intelligence Takeaways (TL;DR)#
- ▸The Post-Software Macroeconomic Regime (): SCENARIO MODEL Global real GDP growth is structurally bounded within a corridor over the next five years. Economic value capture has decoupled from zero-marginal-cost software scaling and migrated downward into five non-substitutable physical, demographic, and monetary bottlenecks. In this regime, aggregate output is governed by a multiplicative O-Ring production architecture where a single physical or monetary choke point throttles the return on all downstream digital capital.
- ▸Lynchpin I — The $29 Trillion Debt Refinancing Wall & Fiscal Dominance: REPORTED FACT Combined global sovereign and corporate gross borrowing reaches $29 trillion in 2026 (including $18 trillion across OECD sovereigns, pushing OECD sovereign bond stocks past $61 trillion or of GDP). With effective interest rates exceeding nominal growth () and of OECD borrowing dedicated strictly to rolling over maturing paper, advanced economies are crossing into Fiscal Dominance. SCENARIO MODEL By 2031, U.S. net federal interest outlays are projected to reach of GDP—matching total Social Security expenditure—forcing central banks toward implicit Yield Curve Control (YCC) and establishing a structural inflation floor.
- ▸Lynchpin II — The Electromechanical & Hydrological Triad: REPORTED FACT More than of planned 2026 U.S. hyperscale data center capacity faces delays or cancellations due to a lead-time siege in Large Power Transformers (LPTs) and Generator Step-Up (GSU) transformers, exacerbated by an U.S. import dependency, a single domestic producer of Grain-Oriented Electrical Steel ( GOES), and municipal watershed blowdown limits. These physical constraints have triggered a Cloud-to-Edge Economic Inversion: enterprise public cloud inference share has fallen to in 2026, accelerating demand for air-gapped, high-unified-memory on-premise appliances (Tresslers Sovereign Node) that operate inside existing commercial building electrical envelopes.
- ▸Lynchpin III — Midstream Refining Monopolies & The November 2026 Cliff: REPORTED FACT Geoeconomic conflict has moved from end-product tariffs to midstream chemical refining blockades. Beijing controls of global gallium () and germanium () refining, of rare earth element () refining, of cathode active materials (), and of refined cobalt (). The expiration of the one-year U.S. export ban suspension on , , and antimony () on November 27, 2026, paired with new November 2026 licensing controls on heavy (, , ) and advanced lithium-ion battery equipment, creates a severe hardware cost wedge between hedged sovereign buyers and unhedged commercial enterprises.
- ▸Lynchpin IV — Demographic Inversion & Embodied AI Labor Substitution: REPORTED FACT With of the U.S. manufacturing workforce aged (and only aged ) amidst a global workforce skill-instability rate, industrial automation is no longer a margin-expansion luxury—it is a survival requirement against physical output contraction. U.S. industrial robot installations are scaling from (2025) to by 2030 (surpassing active units by 2033), requiring unified multi-agent software orchestration (ThinkForge / OpenClaw) and executive cognitive re-architecture (Metanoia Neural Leadership OS).
- ▸Lynchpin V — Bifurcated Trade Blocs & Machine-Native Settlement Rails: REPORTED FACT As the Model Context Protocol (MCP) ecosystem reaches a $10 billion run-rate ( monthly SDK downloads; Fortune 500 adoption), autonomous software agents cannot rely on human-intermediated SWIFT banking or 2.9\% + \0.30\text{USDC}$ enables deterministic, sub-2-second machine-to-machine (M2M) micro-settlement, unlocking programmable liquidity across fragmented geopolitical corridors.
Formal Bayesian Prior & Posterior Derivation#
To quantify the probability of our primary macro-infrastructure thesis—defined as Hypothesis : Simultaneous onset of G7 Fiscal Dominance / Yield Curve Intervention and Enterprise AI Inference Migration from Hyperscale Cloud to On-Premise Sovereign Nodes prior to Q4 2029—the Sovereign Oracle engine updates the institutional consensus prior against four orthogonal empirical evidence vectors observed in Q3–Q4 2026 ():
- ▸: OECD gross sovereign borrowing hitting $18 trillion in 2026 with interest rate mechanics adding to debt-to-GDP ratios ().
- ▸: LPT/GSU transformer lead times reaching with a structural U.S. power transformer deficit ().
- ▸: Broadcom and Deloitte 2026 enterprise telemetry confirming public cloud AI inference share dropping to while of CIOs prioritize sovereign hardware origin and on-prem TCO savings ().
- ▸: Expiration of the November 2026 critical mineral and battery export control cliff alongside a copper tariff regime ().
Assuming conditional independence across the monetary, electromechanical, enterprise survey, and metallurgical evidence streams, the composite likelihood ratio is:
Applying Bayes’ Theorem in odds form:
Converting posterior odds back to probability yields the Sovereign Oracle posterior conviction:
This divergence () represents the primary structural alpha opportunity for sovereign, institutional, and enterprise allocators entering the cycle.
Interactive Telemetry Module 01: Use the Five Lynchpins O-Ring & Fiscal Dominance Simulator below to dynamically adjust the sovereign rate-growth spread (), transformer lead times, critical mineral refining throughput, and Bayesian evidence vectors (), or execute the live
simulate_macro_lynchpinsMCP agent tool directly against/api/mcp.
Cross-Navigation & Companion Intelligence Architecture:
- ▸
For granular metallurgical mass balances on gallium, germanium, and heavy rare earths, cross-reference/insights/critical-minerals-geopolitics-2026.- ▸
For multi-tier industrial vendor auditing and Defense Production Act Section 303 procurement strategy, see/insights/supply-chain-sovereignty-2026.- ▸
For substation interconnect queueing theory and behind-the-meter SMR/micro-turbine siting, consult/insights/sovereign-compute-grids-interconnect-diplomacy-2026.- ▸
For watershed NPDES blowdown thermodynamics and data center cooling physics, see/insights/the-thermodynamic-ledger-2027-2036and/insights/hydrological-thermodynamic-nexus-sovereign-water-2026.
01. The O-Ring Macroeconomic Regime & Post-Software Rent Migration#
Between 2010 and 2024, institutional capital allocation operated under a neoclassical Cobb-Douglas production paradigm characterized by unit elasticity of substitution (). In that regime, abundant zero-interest sovereign credit, slack globalized supply chains, and infinitely replicable cloud software allowed financial and digital capital () to seamlessly substitute for physical friction:
Between 2026 and 2031, this substitutability assumption breaks down completely. A foundation model or an autonomous supply-chain agent cannot synthesize a single token if its host facility lacks a Generator Step-Up transformer, if municipal authorities curtail its evaporative cooling water permit, or if its underlying semiconductor fab is starved of pure refined gallium () and ultra-pure hydrogen fluoride ().
Formal Derivation of the O-Ring Leontief-CES Production Function#
The global economy is governed by a nested Constant Elasticity of Substitution (CES) production function approaching the Leontief complement limit () coupled with Michael Kremer’s O-Ring Production Function:
Where:
- ▸denotes deployed digital and financial capital (cloud software, foundation model weights, liquid credit).
- ▸represents the five physical, demographic, and monetary substrate inputs (: Sovereign Fiscal Capacity, Grid-Water-Compute Infrastructure, Refined Critical Minerals, Embodied Labor/Robotics, and Machine-Native Settlement Liquidity).
- ▸denotes the stochastic bottleneck reliability and throughput coefficient of lynchpin .
- ▸is the elasticity of substitution between digital capital and physical substrates, which empirically satisfies in the industrial buildout.
Taking the partial derivative of aggregate output with respect to digital capital yields the marginal revenue product of software and financial capital:
In the physical bottleneck limit where , total output converges to the minimum binding physical constraint, modulated multiplicatively by the O-Ring reliability cascade:
Whenever any physical substrate becomes the binding constraint (such that ) or its supply-chain throughput probability , the marginal productivity of additional unhedged digital capital collapses toward zero:
Christensen’s Law of Conservation of Attractive Profits#
By Clayton Christensen’s Law of Conservation of Attractive Profits, whenever a previously proprietary, integrated layer of a value chain becomes modularized and commoditized—as foundation model weights and SaaS application wrappers have become via open-weight architectures (DeepSeek-R1/V3, Llama-4, Qwen-3)—economic rents migrate immediately to the adjacent layer that remains non-modular, physically constrained, and integration-intensive.
As illustrated in the system-dynamics architecture above, the five lynchpins do not operate in isolation; they compound one another. Critical mineral refining restrictions (Lynchpin III) inflate the cost and extend the lead times of Grain-Oriented Electrical Steel and copper windings inside Large Power Transformers (Lynchpin II). Transformer and watershed bottlenecks stall hyperscale grid interconnections, forcing enterprises toward local, air-gapped compute appliances and embodied robotics to offset aging industrial labor (Lynchpin IV). Simultaneously, the massive fiscal outlays required to subsidize industrial reshoring, grid hardening, and defense re-industrialization collide with the $29 trillion sovereign and corporate debt maturity wall (Lynchpin I), accelerating the fracture of legacy fiat trade corridors and mandating programmable, machine-native settlement rails (Lynchpin V).
02. Lynchpin I: The $29 Trillion Debt Wall & Fiscal Dominance ()#
The foundational monetary reality of the window is the structural transition of advanced economies from Monetary Dominance—a regime in which independent central banks adjust policy rates freely to anchor inflation expectations while fiscal authorities maintain sustainable primary balances—into Fiscal Dominance, wherein the sheer scale of sovereign debt service and refinancing requirements constrains central bank balance-sheet policy.
The Empirical Scale of the 2026 Sovereign & Corporate Refinancing Wave#
Data synthesized from the OECD Global Debt Report 2026 and the IMF October 2026 Fiscal Monitor confirms that global debt markets have entered an unprecedented rollover regime:
- ▸$29 Trillion Combined Gross Borrowing: REPORTED FACT Total sovereign and corporate gross borrowing globally reaches $29 trillion in 2026, representing a (+$4 trillion) expansion over 2024 levels.
- ▸$18 Trillion OECD Sovereign Issuance: REPORTED FACT Across OECD member states, gross sovereign borrowing reaches a record $18 trillion in 2026 (equivalent to of aggregate OECD GDP), up from $17 trillion in 2025 and more than double the borrowing volume recorded a decade ago. Total outstanding OECD central government marketable bond debt exceeds $61 trillion ( of OECD GDP) in 2026, while total global public debt is on a deterministic trajectory to breach of world GDP by 2029.
- ▸The Refinancing Trap: REPORTED FACT Crucially, nearly of OECD gross sovereign borrowing in 2026—approximately $13.5 trillion—is not funding new productive infrastructure or net fiscal expansion; it is dedicated strictly to refinancing maturing legacy debt originally issued during the zero-interest-rate era ().
- ▸Duration Compression & Treasury Bill Vulnerability: REPORTED FACT Confronted with rising term premia on and sovereign bonds, OECD debt management offices curtailed long-duration issuance in , dropping the ratio of bond issuance relative to maturities to its lowest level since 2008. Sovereign issuers relied on short-term Treasury bills for of total gross issuance, pushing T-bills to of the total outstanding sovereign debt stock. While shortening duration temporarily mitigates long-end yield spikes, it exposes sovereign budgets to immediate repricing velocity whenever short-term rates remain elevated.
Formal Derivation of the Sovereign Debt Trap#
Let denote the sovereign debt-to-GDP ratio in year , where is nominal public debt and is nominal GDP. The law of motion for sovereign debt evolution is given by:
Where is the effective nominal interest rate on the sovereign debt stock, is the primary fiscal balance (revenues minus non-interest expenditures), and represents stock-flow adjustments (e.g., off-budget defense vehicles, state-guaranteed utility bailouts, and FX valuation shifts). Dividing through by nominal GDP and using the Fisher approximation yields the fundamental Sovereign Debt Dynamics Equation:
Where is the effective real interest rate, is the real GDP growth rate, is the primary balance ratio, and . To merely stabilize the debt-to-GDP ratio ( with ), a sovereign must run a debt-stabilizing primary balance of:
In 2026, the global macroeconomic regime suffered a decisive arithmetic inversion:
- ▸The Snowball Effect Turned Positive (): REPORTED FACT Across the OECD, the effective interest rate on sovereign debt stocks rose as maturing low-coupon debt rolled over at market yields above . In 2026, interest rate mechanics added to the aggregate OECD debt-to-GDP ratio, exceeding the debt-erosion benefit of GDP inflation.
- ▸Primary Deficit Divergence: REPORTED FACT Globally, the IMF reports that the average sovereign primary deficit widened to of GDP in 2026 (), whereas the debt-stabilizing primary deficit ceiling required across major economies stood at of GDP—leaving an immediate structural fiscal gap of of global GDP per annum before accounting for aging demographics or defense re-armament.
- ▸The U.S. Entitlement Crossover (): SCENARIO MODEL Globally, the effective average interest cost of government financing is projected by the IMF to climb from (2021) to by 2031. In the United States, net federal interest payments are on pace to surge from of GDP pre-pandemic to of GDP by 2031—at which point federal debt service equals total federal outlays on Social Security.
The Central Bank Endgame: Implicit Yield Curve Control & Financial Repression#
Under standard Monetary Dominance, a central bank follows a Taylor-type reaction function , where the Taylor Principle requires (raising real policy rates when inflation exceeds target ). However, under Fiscal Dominance, when ( of GDP) and of the debt stock sits in short-term T-bills with of gross borrowing tied to rollovers, every increase in feeds directly into the fiscal deficit , expanding the money supply or forcing sovereign bond market illiquidity.
Consequently, between 2027 and 2031, SCENARIO MODEL G7 central banks will be compelled to subordinate strict inflation targeting to sovereign market functioning through three mechanisms of Financial Repression:
- ▸Implicit Yield Curve Control (YCC) & Balance Sheet Liquidity Backstops: Deployed under the nomenclature of "Market Functioning Purchase Programs" or "Standing Repo Operations" whenever 10-year or 30-year sovereign term premia breach debt-sustainability thresholds.
- ▸Prudential Regulatory Captivity: Adjusting Basel III Endgame / sovereign liquidity coverage ratios (LCR) and stablecoin reserve mandates to require commercial banks, pension funds, and regulated fiat-backed stablecoin issuers to absorb higher quotas of domestic Treasury bills and intermediate-duration sovereign paper.
- ▸Structural Inflation Floor (): Because real debt reduction via austerity () is politically unviable across aging democracies and default is unthinkable for reserve-currency issuers, negative real interest rates ( achieved by tolerating nominal inflation while capping nominal yields) become the primary equilibrating valve of the global financial system through 2031.
03. Lynchpin II: The Electromechanical & Hydrological Triad#
While equity markets continue to model Artificial Intelligence and industrial automation as weightless software phenomena governed by Moore’s Law, the physical deployment of compute between 2026 and 2031 is throttled by nineteenth-century electromagnetism and twentieth-century municipal hydrology. Specifically, the global digital buildout has collided with a 200-ton electromechanical bottleneck—the Large Power Transformer (LPT) and Generator Step-Up (GSU) transformer—and watershed thermodynamic limits.
The 128-to-144 Week Transformer Siege & Fleet Senescence#
Every megawatt of utility-scale power generated or consumed by an AI data center campus must pass through multiple voltage transformation stages (). As of Q4 2026, empirical supply-chain telemetry from Wood Mackenzie and the National Infrastructure Advisory Council confirms a severe structural deficit:
- ▸Lead Times & Project Cancellations: REPORTED FACT Over of planned 2026 U.S. data center projects have suffered delays or outright cancellations attributable to transformer unavailability and utility interconnect queues. Industry-wide average lead times stand at () for main substation power transformers and () for Generator Step-Up (GSU) units, with custom high-voltage orders at Tier-1 OEMs backlogged .
- ▸Four Colliding Demand Waves: REPORTED FACT Since 2019, U.S. GSU transformer demand has surged and power transformer demand has climbed , leaving a structural national supply deficit in power transformers and a deficit in distribution transformers, while unit prices have escalated . This demand shock is driven by four simultaneous vectors:
- ▸Hyperscale AI Campuses: Individual training and inference clusters scaling from to , requiring dedicated redundant GSU and substation LPT banks.
- ▸Fleet Senescence: More than of North America’s in-service transformers have exceeded their engineering design life (with average fleet age reaching ), entering the exponential phase of the Weibull insulation failure curve.
- ▸Industrial Reshoring & Electrification: Semiconductor fabs, EV battery gigafactories, and defense manufacturing facilities adding concentrated base-load demand.
- ▸Renewable Grid Interconnections: Utility-scale solar and wind installations requiring roughly more GSU transformer MVA capacity per delivered megawatt-hour than thermal baseload plants due to lower capacity factors.
- ▸
Grain-Oriented Electrical Steel (GOES) Metallurgy & Core Loss Physics#
An LPT cannot be mass-produced on a standard automotive assembly line; it requires bespoke high-voltage winding by master coil technicians (requiring of apprenticeship) around a laminated core of Grain-Oriented Electrical Steel (GOES)—an iron-silicon alloy () cold-rolled and recrystallized to align its body-centered cubic crystal lattice along the Goss texture direction of easiest magnetization.
By Bertotti’s statistical theory of magnetic losses, total specific core power dissipation () in an alternating magnetic field of frequency and peak magnetic flux density is decomposed into hysteresis loss (), classical eddy-current loss (), and anomalous/excess domain-wall loss ():
Where:
- ▸is the lamination thickness (requiring ultra-thin laser-scribed high-permeability Hi-B GOES sheets to suppress eddy currents).
- ▸is electrical conductivity (reduced by adding , as higher silicon concentrations embrittle the strip during cold rolling).
- ▸is mass density ().
REPORTED FACT Because Department of Energy (DOE) efficiency mandates require ultra-low no-load core losses, transformer OEMs cannot substitute standard carbon steel or non-oriented silicon steel without violating thermal ratings. Yet the United States imports roughly of its Large Power Transformers and relies on a single domestic producer (Cleveland-Cliffs) for GOES feedstock, while global high-grade Hi-B GOES rolling capacity is heavily concentrated in Japan, South Korea, China, and Germany. Although the U.S. federal government invoked Defense Production Act (DPA) Section 303 in April 2026 to subsidize and prioritize domestic transformer and GOES capacity, heavy annealing furnace and slitting-line tooling lead times prevent meaningful new North American supply from coming online prior to .
The Hydrological-Thermodynamic Penalty#
Simultaneously, once power reaches the data center rack, of electrical work consumed by silicon switches is dissipated as sensible heat (). As established in our companion dossiers (/insights/the-thermodynamic-ledger-2027-2036 and /insights/hydrological-thermodynamic-nexus-sovereign-water-2026), rejecting of continuous thermal load via traditional open-loop evaporative cooling towers exploits the high latent heat of vaporization of water ( at ), consuming:
Accounting for National Pollutant Discharge Elimination System (NPDES) blowdown conductivity limits across stressed river basins (where cycles of concentration ), gross municipal water withdrawal reaches per campus. Where municipal water authorities impose zero-evaporative permits, operators must pivot to closed-loop mechanical chiller and dry-fluid-cooler arrays. However, because ambient dry-bulb temperatures exceed wet-bulb temperatures by during summer peaks, Carnot chiller compressor work surges, imposing a peak parasitic electrical power penalty—precisely on the grid substations already starved of LPTs.
The Cloud-to-Edge Economic Inversion (Sovereign Node Validation)#
When hyperscale cloud operators face a transformer wait, an substation equipment cost surge, and a dry-cooling power penalty, those structural infrastructure rents are passed directly to enterprise API consumers via rising per-token inference pricing, egress fees, and rate throttling.
This thermodynamic and electromechanical reality explains the decisive shift in 2026 enterprise IT telemetry:
- ▸REPORTED FACT According to the Broadcom 2026 Enterprise AI Survey, the share of enterprise AI inference running on public hyperscale clouds has fallen to , as workloads migrate to private cloud, colocation, and on-premise hardware.
- ▸REPORTED FACT According to the Deloitte 2026 State of AI in the Enterprise Report, of enterprise decision-makers cite vendor country-of-origin sovereignty and total cost of ownership (TCO) savings from on-premise hardware over public cloud APIs as primary procurement mandates.
By deploying Tresslers Sovereign Node Pro ( unified memory, $25,000) or Sovereign Node Enterprise ( multi-node cluster, $75,000–$150,000) inside existing commercial office or factory electrical rooms (drawing off standard building circuits with zero substation upgrades or municipal water permits), enterprises bypass the 3-year grid queue entirely while achieving complete air-gapped data sovereignty.
04. Lynchpin III: Midstream Refining Monopolies & The Critical Mineral Weapon#
Between 2026 and 2031, geopolitical trade conflict has evolved beyond reciprocal border tariffs on finished consumer goods into asymmetric upstream and midstream chemical refining blockades. While Western industrial policy between 2022 and 2025 focused heavily on downstream final assembly (semiconductor packaging, EV assembly, and battery pack integration), Beijing consolidated an overwhelming structural monopoly over the midstream pyrometallurgical and hydrometallurgical refining required to convert raw ore into electronic- and defense-grade precursors.
The Midstream Refining Asymmetry & The November 2026 Export Control Cliff#
Empirical supply-chain audits published by the Council on Foreign Relations (Dismantling China’s Supply-Chain Weapon, September 2026) and the International Energy Agency quantify the severity of this single-jurisdiction concentration:
- ▸Gallium () & Germanium (): REPORTED FACT China controls of global refined gallium and of refined germanium processing. Gallium nitride () and gallium arsenide () are non-substitutable wide-bandgap substrates for AESA radar transmit/receive modules, 5G/6G RF power amplifiers, and high-efficiency AI data center server power supplies. Following the temporary one-year diplomatic suspension agreed to in late 2025, China’s outright export ban suspension on , , and antimony () to the United States expires on November 27, 2026, reverting to strict end-user state licensing and dual-use military prohibitions.
- ▸Rare Earth Elements () & High-Coercivity Permanent Magnets: REPORTED FACT China commands of global rare earth chemical refining and over of sintered Neodymium-Iron-Boron () permanent magnet metallization. Critically, for high-temperature operation inside industrial robotics actuators, EV traction motors, and defense guidance fins (operating at ), lattices must be grain-boundary-diffused with Heavy Rare Earth Elements (HREEs)—specifically Dysprosium () and Terbium ()—alongside Samarium-Cobalt () magnets for aerospace environments. In November 2026, Beijing’s expanded export control framework takes effect across five additional rare earth elements, specialized magnet-manufacturing equipment, and midstream separation technologies.
- ▸Cathode Active Materials () & Battery Tooling: REPORTED FACT China controls of global Cathode Active Material () production, of global lithium-ion battery cell manufacturing, and of refined cobalt (). The November 2026 export control tranche explicitly targets high-energy-density battery architectures, precursor synthesis equipment, and synthetic graphite spheronization machinery—directly impacting utility-scale Battery Energy Storage Systems (BESS) needed to buffer AI data centers and microgrids.
- ▸The Copper () & Semiconductor Process Gas Chokepoint: SCENARIO MODEL Electrification, grid upgrades, and liquid-cooled AI racks face a structural global refined copper deficit projected to exceed by 2030, compounded in the U.S. by tariff pressures on semi-fabricated copper products and a geographic concentration in ultra-pure semiconductor process gases and wet chemicals (including tungsten hexafluoride , nitrogen trifluoride , neon , and electronic-grade hydrofluoric acid ).
Thermodynamic & Chemical Reality of Midstream Substitution#
Rebuilding midstream chemical refining outside China cannot be accomplished on software timelines because solvent-extraction separation of lanthanides () is governed by minuscule differences in trivalent ionic radii (the lanthanide contraction), requiring sequential mixer-settler stages operating with concentrated hydrochloric or nitric acid () and organophosphorus extractants (such as or ), alongside radioactive thorium () and uranium () tailings management.
To bypass multi-year greenfield mining permits during the window, industrial capital is pivoting toward two non-traditional extraction architectures analyzed by Tresslers Deep Research Advisory:
- ▸Thermally Coupled Direct Lithium & Mineral Extraction (DLE): Utilizing gibbsite-derived layered double hydroxide sorbents () and crown-ether ion-exchange membranes to selectively strip , , and bromides from domestic oilfield produced brines (Smackover Formation) and concentrated industrial reject streams, using low-grade data center waste heat () to drive sorbent elution kinetics.
- ▸Closed-Loop Hydrometallurgical Urban Mining: Automated robotic disassembly and organic-acid leaching of decommissioned telecom switching gear, server motherboards, and end-of-life permanent magnets, recovering , , , , , and at concentrations higher than virgin run-of-mine ore.
05. Lynchpin IV: The Demographic Inversion & Embodied AI Labor Substitution#
Between 2026 and 2031, the global labor supply undergoes an irreversible structural bifurcation: acute working-age population contraction across advanced economies and East Asia colliding with rapid technological skill obsolescence.
The Demographic Cliff in Industrial Manufacturing#
Empirical labor force metrics from the U.S. Bureau of Labor Statistics, the National Association of Manufacturers, and the World Economic Forum (Future of Jobs Report 2025–2030) establish the quantitative contours of this demographic inversion:
- ▸The Aging Industrial Core: REPORTED FACT The United States accounts for of global manufacturing value added—exceeding the combined manufacturing output of Japan, Germany, South Korea, Italy, and France. Yet within the U.S. manufacturing workforce, of all workers are aged or older, while only are aged . As the remaining Baby Boomer master machinists, tool-and-die makers, high-voltage linemen, and welding inspectors retire between 2026 and 2031, the incoming Gen-Z cohort is less than one-third the size required for replacement.
- ▸The Skill-Instability Shock: REPORTED FACT Across the global workforce, of core job skills will be transformed or rendered obsolete between 2025 and 2030. Structural labor market churn over this five-year window equals of all formal global employment—comprising gross new job creation ( roles) offset by outright structural destruction ( roles), yielding a net gain of ( jobs) but requiring out of every workers globally to undergo structural reskilling by 2030.
- ▸Immigration & Labor Supply Elasticity: Tighter border and visa enforcement across North America and Western Europe in has lowered the wage elasticity of blue-collar labor supply (). Raising nominal wages in isolated industrial corridors no longer summons an elastic pool of skilled tradespeople; without automation, wage inflation simply cannibalizes operating margins without expanding physical throughput.
The Embodied AI & Industrial Robotics Acceleration ()#
Consequently, the deployment of embodied AI—vision-language-action (VLA) foundation models integrated into 6-axis industrial arms, autonomous mobile robots (AMRs), and dexterous bipedal/wheeled manipulators—has shifted from speculative R&D to defensive industrial capex:
- ▸U.S. Robotics Fleet Trajectory: SCENARIO MODEL Annual U.S. industrial robot installations are accelerating from in 2025 to by 2030 (a CAGR), putting the United States on a deterministic trajectory to surpass active operational industrial robots by 2033.
- ▸Automation Earnings Inflection: REPORTED FACT In Q2 2026, global factory automation primes recorded year-over-year top-line revenue growth and a surge in operating profit, confirming that manufacturers are aggressively substituting embodied capital for scarce demographic labor.
Formal Condition for Embodied Capital Substitution#
Let denote the fully burdened annual cost of a human industrial operator (growing at wage-scarcity rate ), and let denote the annualized user cost of an embodied robotic workcell with acquisition cost , depreciation and maintenance rate , sovereign-influenced cost of capital , electrical consumption , and supervisory agentic orchestration overhead :
Defining the effective productivity-adjusted substitution threshold where is the task-completion reliability of the VLA-driven robot relative to human dexterity :
Whenever , capital deterministically replaces labor. In 2026, with hardware unit costs falling at for standard dexterous workcells and VLA fine-tuning pushing past in structured warehouse, CNC tending, and PCB assembly environments, has crossed across two-shift and three-shift North American operations.
The Supervisory Bottleneck: Productive Jobless Growth & Neural Leadership#
As both the IMF and Schroders 2026 macroeconomic outlooks warn, the rapid substitution of digital and embodied AI for routine cognitive and physical labor creates a macro-distributional paradox: "highly productive, jobless growth." Total factor productivity () and capital share of income rise, while middle-tier administrative and junior analytical entry pathways contract. Inside the enterprise, however, the primary failure mode of 2026 AI and robotics deployments is not hardware mechanics—it is organizational and supervisory friction.
Human executives and middle managers trained for linear, human-only span-of-control hierarchies struggle to govern asynchronous fleets of autonomous software agents and physical robots. Tresslers Group addresses this exact human-machine boundary through a dual architecture:
- ▸ThinkForge Agentic Orchestration (
OpenClaw): Deploying deterministic, local-first multi-agent supervisory meshes that coordinate ERP, MES, procurement, and robotic telemetry on air-gapped Sovereign Nodes. - ▸Metanoia Neural Leadership OS: Re-architecting executive cognitive load, decision latency, and supervisory governance so human leaders transition from manual workflow routers into high-leverage Architects of Autonomous Systems.
06. Lynchpin V: Geoeconomic Bifurcation & Machine-Native Settlement Rails (x402 / AP2)#
The fifth lynchpin binds the monetary, physical, and agentic layers together: how value is priced, metered, and settled across a fractured global economy populated by autonomous software agents.
REPORTED FACT Between 2026 and 2031, global trade is bifurcating into competing regulatory and currency spheres while inside the enterprise, the Model Context Protocol (MCP) ecosystem has scaled into a $10 billion market with monthly SDK downloads and penetration across the Fortune 500.
The Structural Incompatibility of Legacy Financial Plumbing#
When an autonomous procurement agent, an edge Sovereign Node, or an embodied factory controller needs to purchase a real-time macroeconomic risk vector from the Sovereign Oracle API ($0.25), lease of burst GPU compute ($0.04), or settle an automated behind-the-meter kilowatt-hour balance, legacy human-centric payment rails fail on three mathematical and operational fronts:
- ▸Fixed Fee Asymmetry: Traditional payment processors (Visa/Mastercard interchange rails) charge a fixed base fee plus a percentage: . For a micro-transaction of value v = \0.05$, the effective transaction fee rate is: This renders sub-dollar metered API and machine-to-machine (M2M) commerce economically impossible on legacy rails.
- ▸Identity & KYC Incompatibility: Autonomous AI agents (
OpenClawinstances, MCP clients) do not possess government-issued photo IDs, physical residential addresses, or wet-ink signatures required to open traditional commercial bank accounts, nor can they pass human-interactive CAPTCHA or SMS 2FA challenges during a API call. - ▸Settlement Latency & Chargeback Risk: Cross-border SWIFT wires require and incur $15 to $45 correspondent banking deductions, while credit card transactions carry a reversible chargeback window—an unacceptable counterparty risk when delivering irreversible cryptographic intelligence or real-time compute cycles to an anonymous remote agent.
Technical Architecture of HTTP 402 (x402), Permit2 Upto, and AP2#
REPORTED FACT In 2026, the activation of the x402 Protocol—stewarded by the Linux Foundation x402 Foundation alongside Coinbase Developer Platform (CDP), Cloudflare, and Stripe’s 2026-05-27.preview multi-chain machine payment deposit mode—together with Google’s Agent Payments Protocol (AP2), resolves this bottleneck by activating the long-dormant HTTP 402 Payment Required status code as a native, cryptographic machine settlement layer over Base L2 and Solana in .
With over cumulative x402 transactions processed and native integrations spanning Apify agentic scrapers and enterprise MCP gateways, the protocol replaces SaaS seat subscriptions with deterministic, usage-metered cryptographic settlement:
- ▸Uniswap Permit2
UptoMetered Allowances: Rather than signing and broadcasting a separate on-chain transaction for every sub-cent token generation or streaming API chunk, the client agent signs an off-chain EIP-712 typed data structure granting a boundedPermit2Uptoallowance (e.g., ) valid only for a specific recipient contract, nonce, and expiration timestamp . As the server streams tokens or telemetry packets , the actual settled amount is finalized atomically upon stream completion. - ▸Hardware-Enforced Agentic Wallets (TEE Policy Engines): Enterprise agents operate non-custodial wallets inside Trusted Execution Environments (AWS Nitro Enclaves / Coinbase CDP Server Wallets) governed by deterministic policy guardrails (e.g., maximum daily spend , whitelisted destination contracts only, zero human private-key exposure).
Through the Tresslers Machine Intelligence Protocol (MIP) Gateway Proxy, enterprises and third-party API providers wrap any existing REST or MCP endpoint in an x402/AP2 settlement perimeter in minutes—capturing instant global liquidity while Tresslers accrues a $99/month SaaS gateway license plus a protocol settlement fee on every autonomous transaction.
Interactive Telemetry Module 02: Use the Cloud-to-Edge Sovereign Node TCO & x402 Machine Settlement Workbench below to model 5-year cumulative enterprise compute outflows, Bertotti GOES transformer core losses, and step-by-step HTTP 402 (
x402)Permit2Uptocryptographic settlement payloads.
07. Quantitative Reference Matrices & Strategic Playbook ()#
Table 1: 5-Year Sovereign Debt & Fiscal Dominance Matrix ()#
| Sovereign Bloc / Jurisdiction | 2026 Gross Sovereign Borrowing | 2026 Sovereign Debt-to-GDP () | 2031 Projected Debt-to-GDP () | Net Interest Outlays (% of GDP: ) | Rollover & Short-Term Vulnerability Metric | Primary 2026–2031 Monetary Endgame |
|---|---|---|---|---|---|---|
| United States | \approx \11.4\text{T}$ (incl. T-bill roll) | (General Govt) | (equals Social Security by 2031) | T-bills at of marketable debt; weighted maturity | Implicit YCC via Treasury buybacks, Fed balance sheet floor & stablecoin T-bill absorption | |
| OECD Aggregate | \18.0\text{T}24%$ of OECD GDP) | (\61\text{T}$ bond stock) | of gross borrowing (\13.5\text{T}15%$ | Prudential bank LCR captivity; structural inflation floor of to force | ||
| Euro Area (Aggregate) | \approx \3.4\text{T}$ equivalent | (France , Italy ) | Fragmentation spread risk between core (Bunds) and high-debt sovereigns + defense spending surge | Activation of ECB Transmission Protection Instrument (TPI) & joint EU defense bond issuance | ||
| Japan | \approx \2.1\text{T}$ equivalent | Every JGB yield shift adds of GDP to debt service by 2030 | Ongoing BoJ balance-sheet intervention; structural yen volatility against real assets | |||
| Global Total (Sovereign + Corporate) | **\29.0\text{T}+17%$ vs. 2024) | (Public Debt / World GDP) | (Breaches by 2029) | Global effective govt interest rate: | Global primary deficit at of GDP vs. stabilizing threshold | Migration from fiat duration bonds into bottleneck real assets, local compute & programmable |
Table 2: Electromechanical, Hydrological & Critical Mineral Bottleneck Matrix ()#
| Physical Substrate / Component | 2026 Global / U.S. Supply Deficit or Monopoly Share | 2026 Procurement Lead Time & Price Escalation | Governing Physical / Chemical Constraint | November 2026 Policy / Geopolitical Trigger | Tresslers Ecosystem Mitigation Vector |
|---|---|---|---|---|---|
| Generator Step-Up (GSU) Transformers | demand surge since 2019; U.S. import reliance | avg ( Tier-1 custom); price | Bespoke high-voltage coil winding & Hi-B GOES core laminations | April 2026 DPA Sec. 303 invoked; new domestic capacity delayed until | Bypass utility substation upgrades via local Sovereign Node () building power |
| Large Power Transformers (LPTs) | structural U.S. supply deficit; demand surge | avg; unit price since 2019 | of U.S. grid transformers exceed design life | of 2026 U.S. hyperscale data center builds delayed or cancelled | Behind-the-meter micro-utilities + air-gapped edge AI inference clusters |
| Grain-Oriented Electrical Steel (GOES) | 1 domestic U.S. producer; global Hi-B rolling in JP/KR/CN/DE | for laser-scribed core strip | Goss texture secondary recrystallization & Bertotti eddy loss () | Section 232 tariff frictions on imported laminations & transformer cores | Deep Research Advisory vendor audits & amorphous-metal distribution core substitution |
| Data Center Cooling Water () | evaporated per ( gross) | NPDES & municipal watershed permit queues | Latent heat ; dry cooling adds peak kW penalty | Municipal zero-evaporative moratoria across Southwestern U.S., Virginia & EU | Closed-loop direct-to-chip dielectric liquid cooling + thermal brine valorization (DLE) |
| Refined Gallium () & Germanium () | Chinese refining share | Spot premia outside state quotas | Trace byproduct of bauxite/alumina Bayer liquor () and zinc smelter flue dust () | Nov 27, 2026 expiration of 1-year U.S. export ban suspension (reverts to state block) | Sovereign stockpiling & secondary recovery from semiconductor wafer kerf/scrap |
| Heavy Rare Earths (, , ) & | Chinese REE refining; CAM; Co refining | to permit & commission non-Chinese solvent extraction | stage mixer-settler lanthanide separation + radioactive tailings | Nov 2026 export controls on 5 additional REEs, , and lithium-ion battery tooling | Urban hydrometallurgical magnet recycling & cerium/iron-nitride magnet substitution |
Table 3: 5-Year Enterprise AI Compute TCO & Latency Matrix ()#
Scenario Baseline: Mid-to-large enterprise processing tokens/month of sensitive financial, legal, and industrial telemetry ( class reasoning & coding models + multi-agent OpenClaw orchestration) over a horizon.
| Evaluation Dimension | Unhedged Public Hyperscale Cloud API | Cloud Dedicated VPC / Managed Instance | Tresslers Sovereign Node Pro (Single Appliance) | Tresslers Sovereign Node Enterprise (3-Node Cluster) |
|---|---|---|---|---|
| Hardware / Architecture Spec | Multi-tenant shared cloud GPU cluster (metered per token) | Rented cloud instance ( reserved) | Unified Memory local appliance + OpenClaw OS | Unified Memory high-availability cluster |
| Upfront CapEx (Year 0) | $0 | $0 (requires contractual commitment) | $25,000 (turnkey hardware + local stack) | $75,000–$150,000 (modeled at $110,000 mid-point) |
| Annualized Power, API & Grid Pass-Through Escalation | (LPT delays, dry-cooling kW tax & sovereign tariff pass-through) | (colocation power & egress surcharges) | standard wall circuit (\approx \1,580\text{/yr}$ power; zero grid queue) | existing server closet (\approx \5,500\text{/yr}$ power; zero substation wait) |
| 5-Year Cumulative Cash Outflow () | $1,189,800 ($180k/yr base escalating at ) | $1,494,600 ($240k/yr base escalating at ) | $56,900 ($25k CapEx + $4.8k/yr support + $1.58k/yr power) | $197,500 ($110k CapEx + $12k/yr support + $5.5k/yr power) |
| 5-Year Net TCO Savings vs. Public Cloud | Baseline () | -\304,800-25.6%$ worse) | +$1,132,900 ( reduction) | +$992,300 ( reduction) |
| First-Token Latency & Jitter () | (subject to regional API congestion) | (WAN round-trip overhead) | (local LAN / zero WAN transit) | (local RDMA / Thunderbolt 5 fabric) |
| Data Sovereignty & Regulatory Posture | Exposed to cloud provider telemetry, subpoena & external network outages | Logical isolation only; weights & prompts traverse third-party hardware | 100% Air-Gapped / Zero External Egress (ITAR, HIPAA, SEC, Defense ready) | 100% Air-Gapped / Cryptographically Attested with x402 local gateway |
Table 4: Sovereign Oracle Prediction-Market Divergence & Decision-Maker Directives (DMD)#
| Macroeconomic Lynchpin | Prediction Market / Consensus Pricing (Q4 2026) | Sovereign Oracle Posterior () | Alpha Gap () | Immediate Decision-Maker Directive () | Strategic 5-Year Positioning () |
|---|---|---|---|---|---|
| 1. Fiscal Dominance & G7 Yield Curve Intervention | odds of G7 central bank balance-sheet cap on long-end yields by 2029 | Reduce unhedged long-duration nominal sovereign bond exposure; lock fixed-rate corporate credit before term premia steepen further. | Overweight hard physical bottleneck assets (, GOES steel, water rights, behind-the-meter power) and programmable velocity rails. | ||
| 2. Cloud-to-Edge Enterprise AI Migration ( On-Prem) | odds of Fortune 2000 AI inference running on-prem by Q4 2029 | Audit all recurring hyperscale LLM API spend > \10,000\text{/mo}$; deploy Sovereign Node Pro/Enterprise to cap inference TCO and eliminate WAN latency. | Establish autonomous behind-the-meter compute enclaves immune to utility transformer queues and municipal water curtailments. | ||
| 3. Critical Mineral & Battery Export Blockade Persistence | odds that Nov 2026 controls remain active through 2029 | Execute Tier-2/Tier-3 BOM bills-of-material audits for , magnets (), and Chinese across all hardware capex. | Co-invest in thermally coupled Direct Lithium/Mineral Extraction (DLE) and domestic closed-loop hydrometallurgical urban mining off-take agreements. | ||
| 4. Embodied AI & Agentic Supervisory Adoption | odds of U.S. annual robot installs hitting by 2030 with agentic MES control | Map workflow bottlenecks where workforce age exceeds or skill churn exceeds ; deploy ThinkForge (OpenClaw) supervisory agents. | Pair physical workcell automation with Metanoia Neural Leadership OS to eliminate middle-management cognitive bottlenecks. | ||
5. Machine-Native Settlement (x402 / AP2) Dominance | odds that HTTP 402 / L2 stablecoins capture of paid MCP API traffic by 2029 | Wrap proprietary enterprise data feeds and MCP servers in the Tresslers x402 MIP Gateway Proxy using Permit2 Upto metered settlement. | Transition enterprise B2B telemetry, compute leasing, and supply-chain micro-invoicing from fiat wires to deterministic sub-2-second Base/Solana rails. |
08. Agentic Execution Interface & MCP Tool Manifest (TG-MACRO-2026-011)#
Autonomous AI agents, quantitative research pipelines, and OpenClaw supervisory nodes can programmatically ingest, query, and stress-test the mathematical models in this dossier via the Tresslers Sovereign MCP Gateway (https://tresslersgroup.com/api/mcp).
{
  "mcp_endpoint": "https://tresslersgroup.com/api/mcp",
  "dossier_slug": "five-physical-monetary-lynchpins-global-economy-2026-2031",
  "dossier_id": "TG-MACRO-2026-011",
  "settlement_protocol": "x402-permit2-upto (Base Mainnet Chain ID 8453 / USDC)",
  "callable_agent_tools": [
    {
      "name": "simulate_macro_lynchpins",
      "tier": "FREE (Tier 0)",
      "description": "Deterministic 2026-2031 Five Lynchpins macroeconomic & Sovereign Node TCO simulator.",
      "sample_jsonrpc_call": {
        "jsonrpc": "2.0",
        "method": "tools/call",
        "params": {
          "name": "simulate_macro_lynchpins",
          "arguments": {
            "r_minus_g_bps": 65,
            "primary_deficit_pct_gdp": 3.3,
            "lpt_lead_time_weeks": 136,
            "mineral_refining_reliability_pct": 68,
            "vla_robotics_reliability_ratio": 0.88,
            "monthly_enterprise_tokens_billions": 1.5,
            "x402_transaction_value_usdc": 0.25
          }
        },
        "id": 1
      }
    },
    {
      "name": "read_dossier",
      "tier": "Preview FREE / Full Decryption $0.50 USDC (x402)",
      "arguments": {
        "slug": "five-physical-monetary-lynchpins-global-economy-2026-2031"
      }
    },
    {
      "name": "query_knowledge_graph",
      "tier": "1-Hop FREE / 2-3 Hops $0.10 USDC (x402)",
      "arguments": {
        "entity_id": "x402",
        "depth": 2
      }
    }
  ]
}
09. Verified Institutional References & Epistemic Audit Trail#
- ▸Organisation for Economic Co-operation and Development (OECD): Global Debt Report 2026: Sustaining Debt Market Resilience Under Growing Pressures, OECD Publishing, Paris (March 2026). Empirical source for $29 trillion global combined borrowing, $18 trillion OECD sovereign borrowing, $61 trillion OECD marketable bond stock ( of GDP), refinancing ratio, Treasury bill stock share, and interest rate contribution to debt-to-GDP.
- ▸International Monetary Fund (IMF): Fiscal Monitor: Fiscal Policy in an Era of High Debt and Geoeconomic Fragmentation & World Economic Outlook, Washington, D.C. (October 2026). Empirical source for global public debt crossing of GDP by 2029, global average primary deficit of of GDP vs. debt-stabilizing threshold, global effective government financing rate rising from (2021) to (2031), and U.S. net interest payments trending to of GDP by 2031.
- ▸Wood Mackenzie & National Infrastructure Advisory Council (NIAC): North America Power Transformer Market Outlook & Grid Bottleneck Assessment (2025–2026) and White House Presidential Determination under Defense Production Act (DPA) Section 303 (April 2026). Empirical source for LPT and GSU lead times, GSU and power transformer demand growth since 2019, power transformer supply deficit, U.S. LPT import share, single domestic GOES producer, and of U.S. transformers exceeding their design life.
- ▸Council on Foreign Relations (CFR): Dismantling China’s Supply-Chain Weapon: Critical Minerals, Refining Monopolies, and National Security (September 2026) and Ministry of Commerce of the People's Republic of China (MOFCOM) Export Control Announcements (2025–2026). Empirical source for gallium/germanium refining share, rare earth refining share, cathode active material () share, cobalt refining share, and the November 27, 2026 expiration of the one-year suspension on alongside November 2026 battery and REE export controls.
- ▸World Economic Forum (WEF) & International Federation of Robotics (IFR): The Future of Jobs Report 2025–2030 (Geneva) and World Robotics Industrial Report (2025–2026). Empirical source for global workforce skill-instability rate, structural job churn ( creation / destruction), reskilling requirement by 2030, of U.S. manufacturing workforce aged vs. aged , and U.S. industrial robot shipments scaling from to by 2030.
- ▸Broadcom, Deloitte & Linux Foundation x402 Foundation: Broadcom 2026 Enterprise AI Infrastructure Survey; Deloitte 2026 State of AI in the Enterprise Report; x402 Protocol Specification (Coinbase CDP / Cloudflare / Stripe
2026-05-27.previewMachine Payments); and Google Agent Payments Protocol (AP2) Technical Standard (2026). Empirical source for public cloud inference share, enterprise sovereign origin and on-prem TCO priority, $10 billion MCP market ( monthly SDK downloads), and Permit2Uptodeterministic settlement metrics.